A faster way in.
A low-friction account-opening journey balancing speed, compliance and fraud prevention.
Identity · Documents · Biometrics · Account setup
Explore ↓My contribution
I led the complete onboarding journey.
The work combined journey architecture and interaction design with A/B testing, compliance requirements and fraud-prevention constraints. The objective was to reduce effort without weakening the controls required for a regulated financial product.
- ProblemFriction across a regulated onboarding journey
- My roleDesign Lead · End-to-end journey architecture
- Key decisionProgressive verification on one shared backbone
- Evidence30% faster · 23-competitor benchmark
01 / The problem
Make regulation feel almost invisible.
Account opening was both a regulated journey and a core acquisition lever.
Every unnecessary step increased friction, but identity checks, document capture, biometric validation and fraud controls could not simply be removed. The challenge was to make those requirements clear, progressive and low effort.
02 / Journey architecture
Design the connected system, not isolated screens.
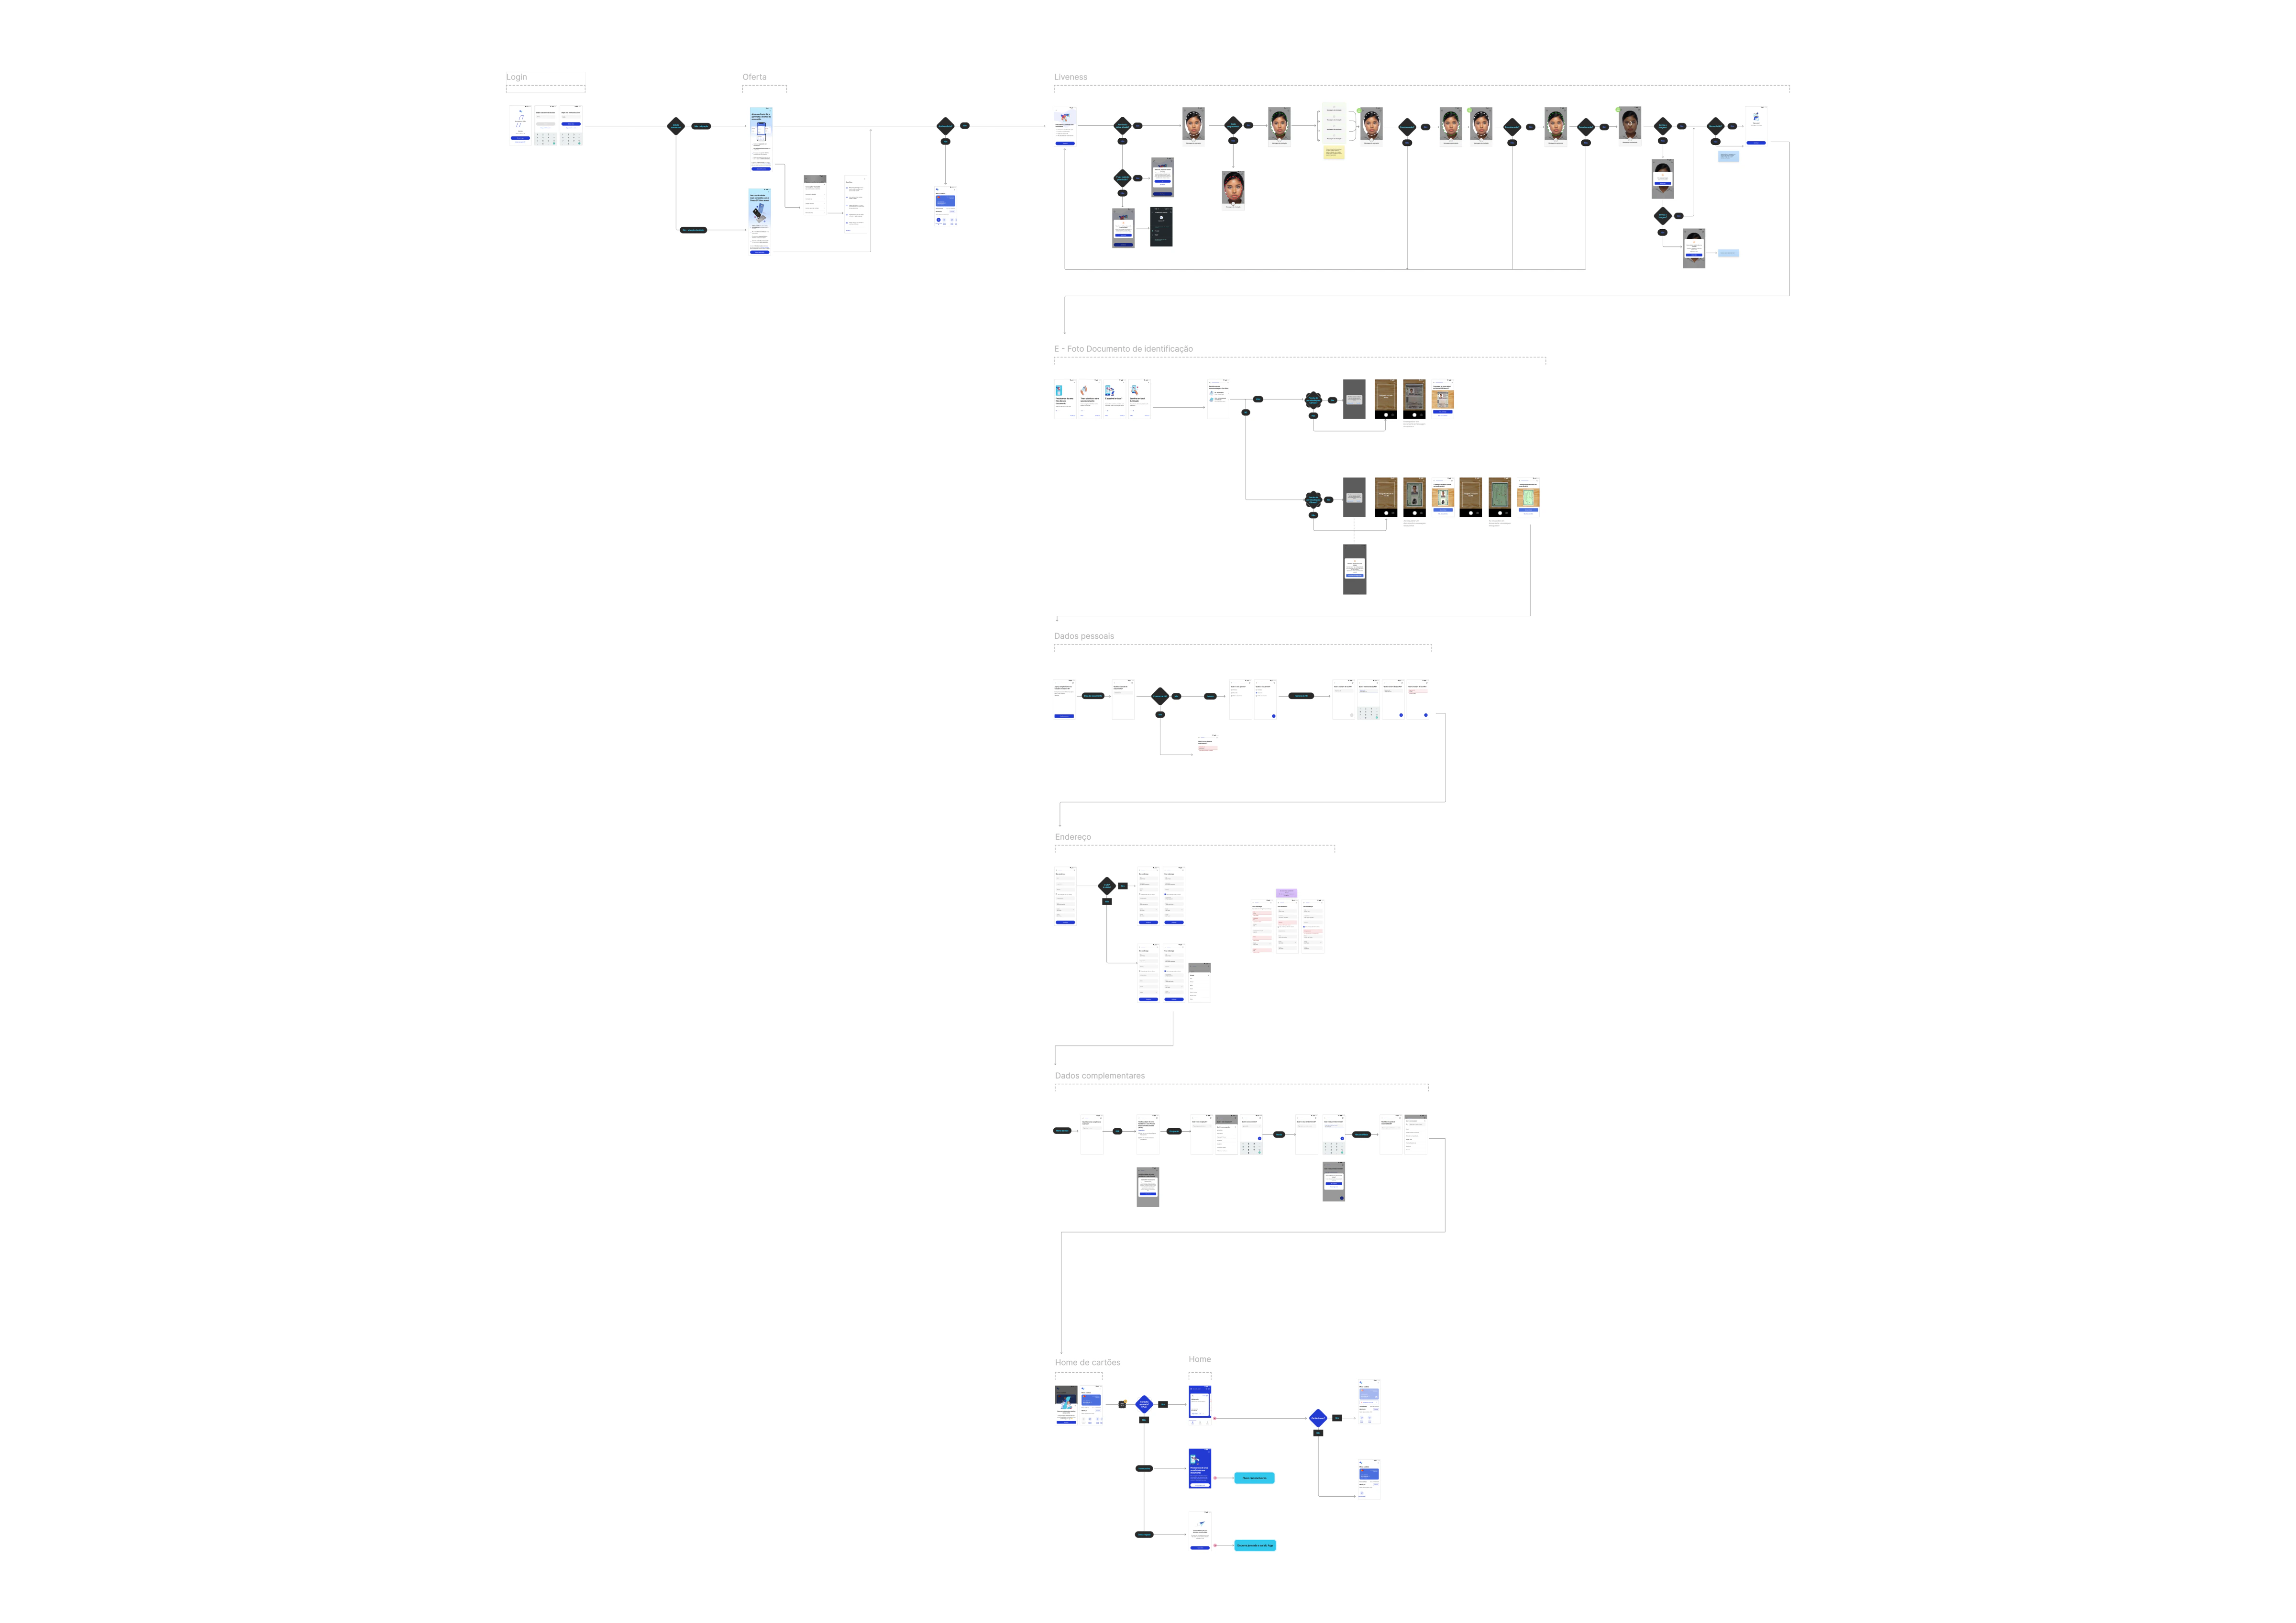
The onboarding backbone connected the whole path from first offer to an active account.
- Identity recognition and document capture.
- Biometric validation and fraud prevention.
- Compliance requirements and exception paths.
- Account and card setup, refined through A/B testing.
Reported external benchmark
30% faster across a 23-competitor benchmark.
The journey was reported as faster in an idwall benchmark spanning 23 competing account-opening experiences.
Reported idwall benchmark · 23 competitors
03 / Offer and usability
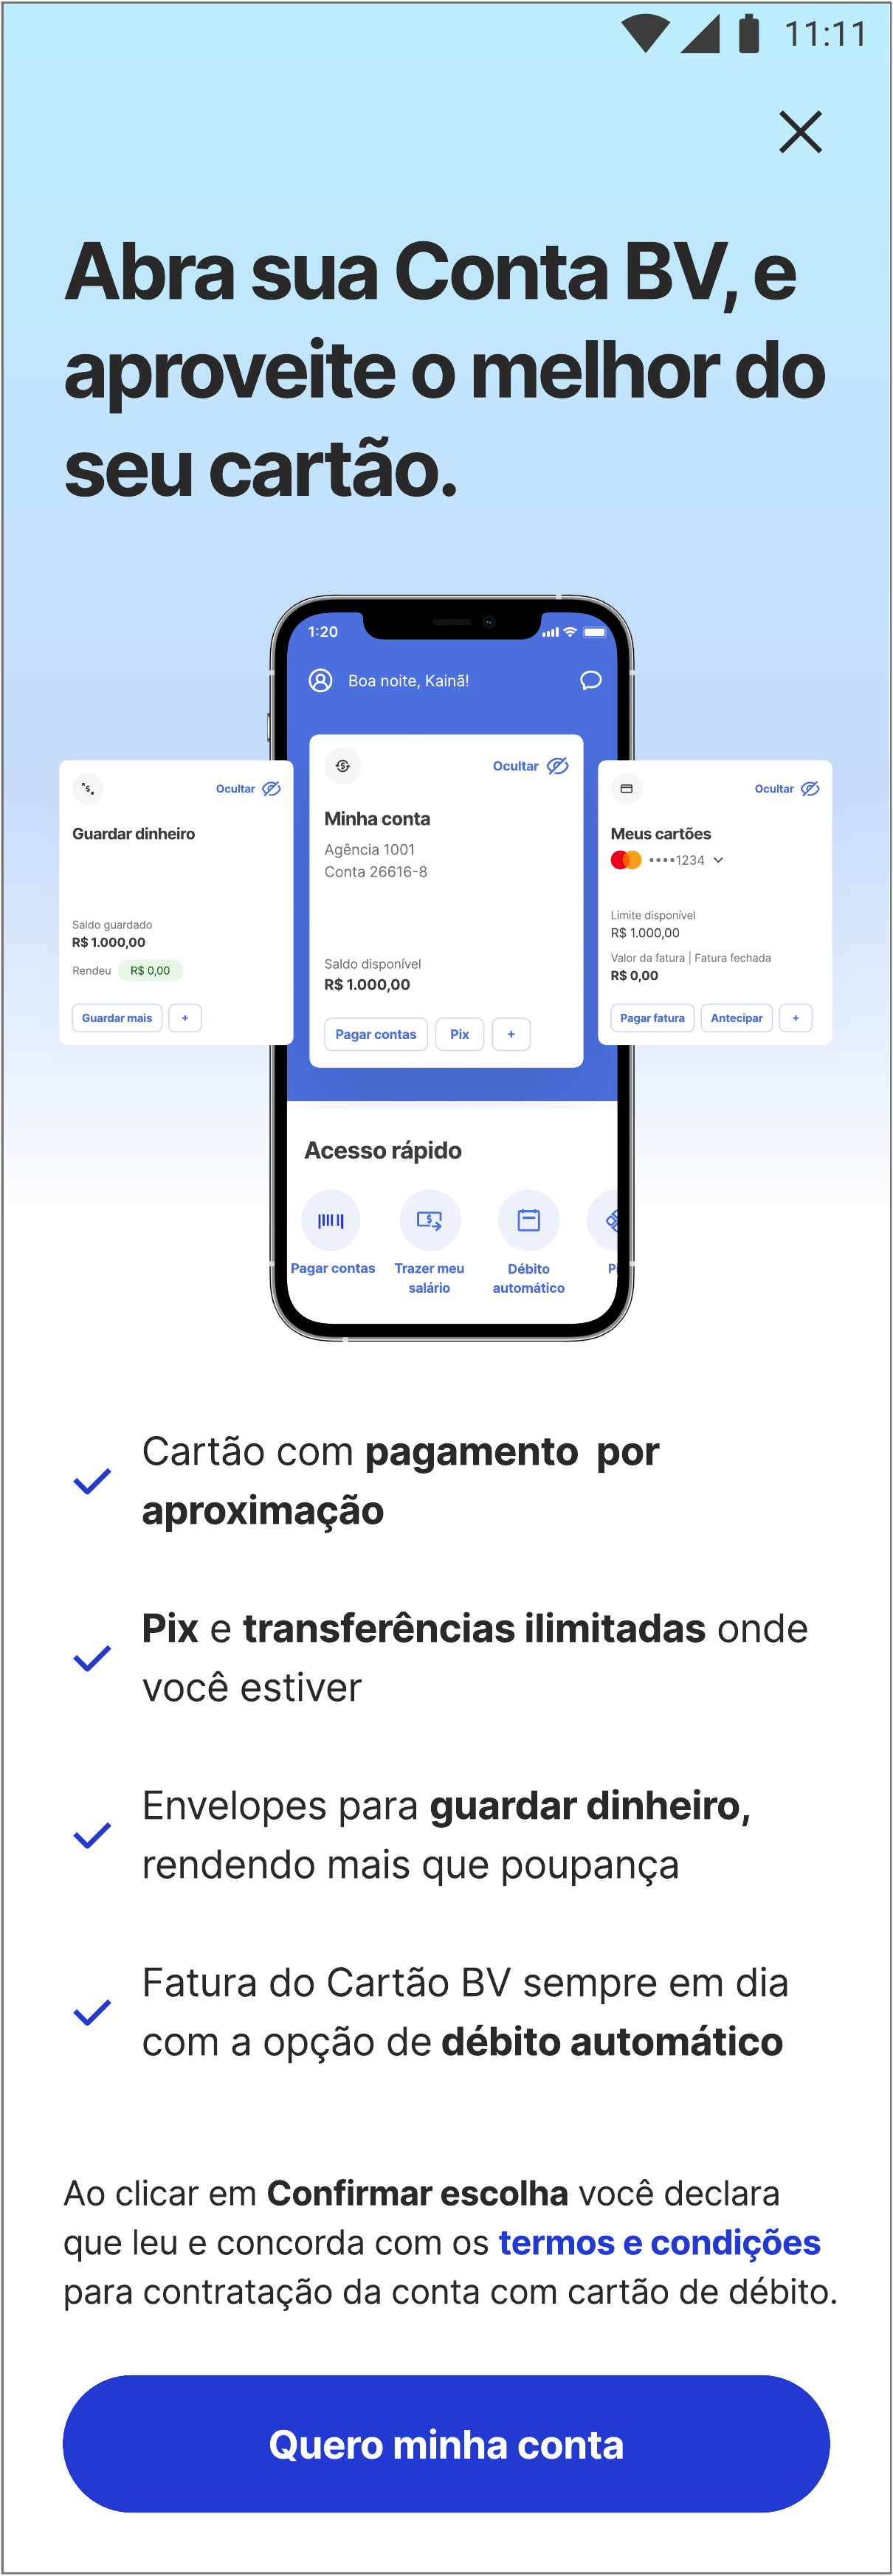
Show the account taking shape.
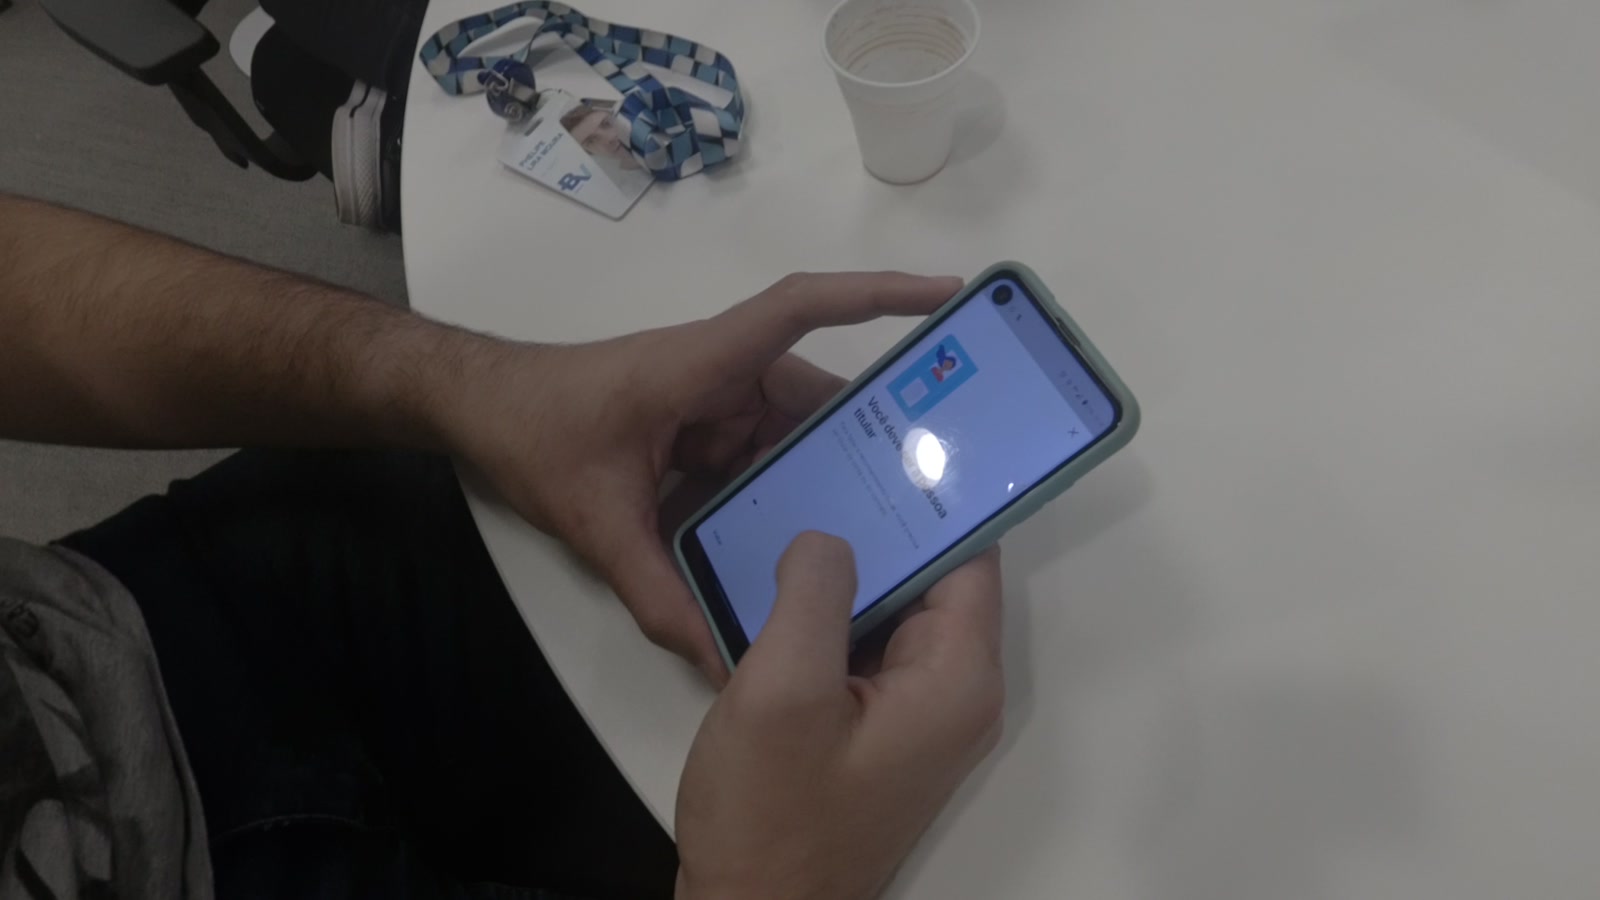
“I didn’t even notice I had opened an account. It just happened.”
04 / Document capture
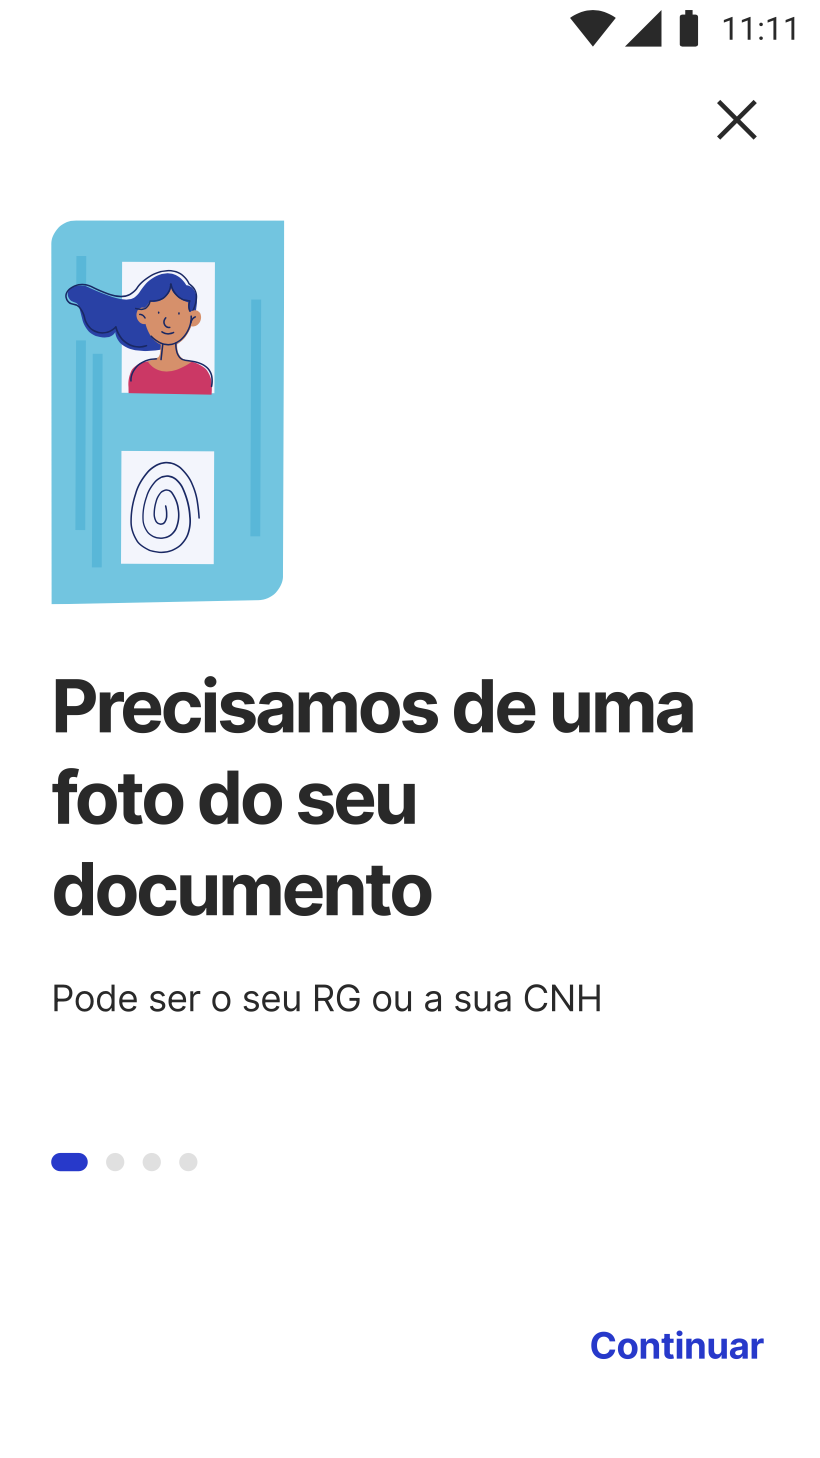
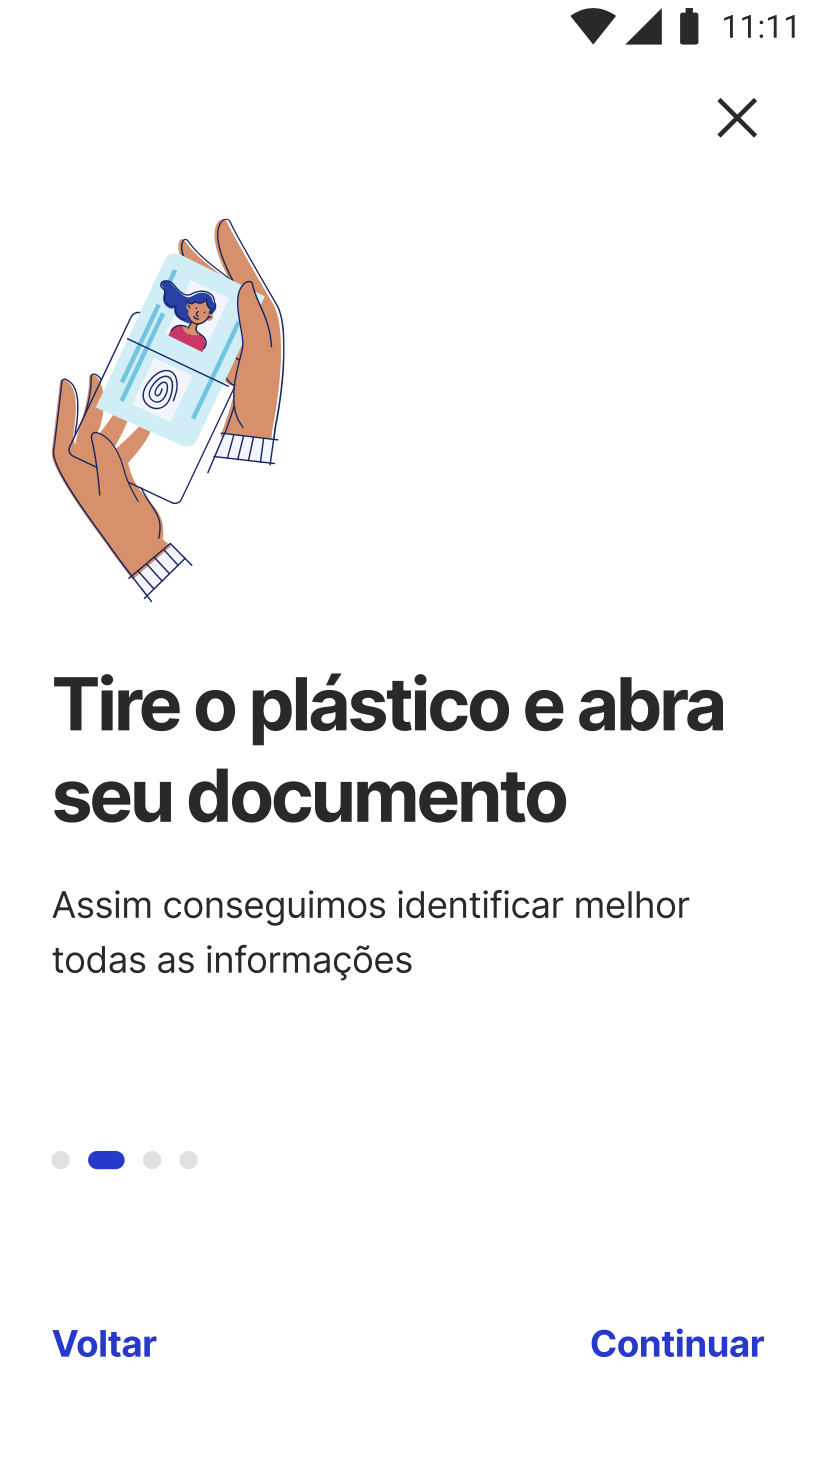
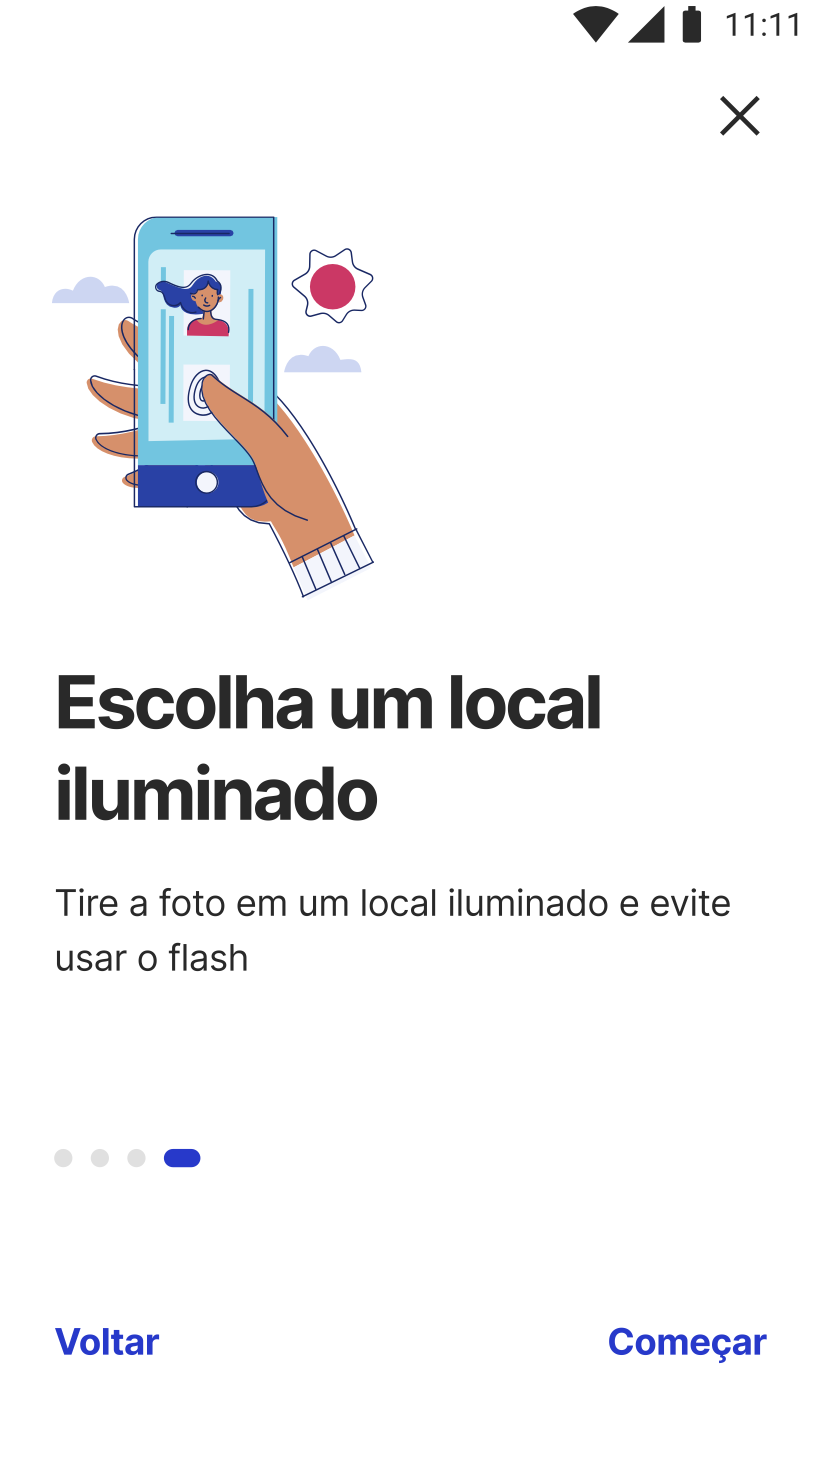
Prepare people before opening the camera.
The interface turned a compliance requirement into a sequence of small, actionable instructions.
05 / Account and card setup
Continue beyond verification.
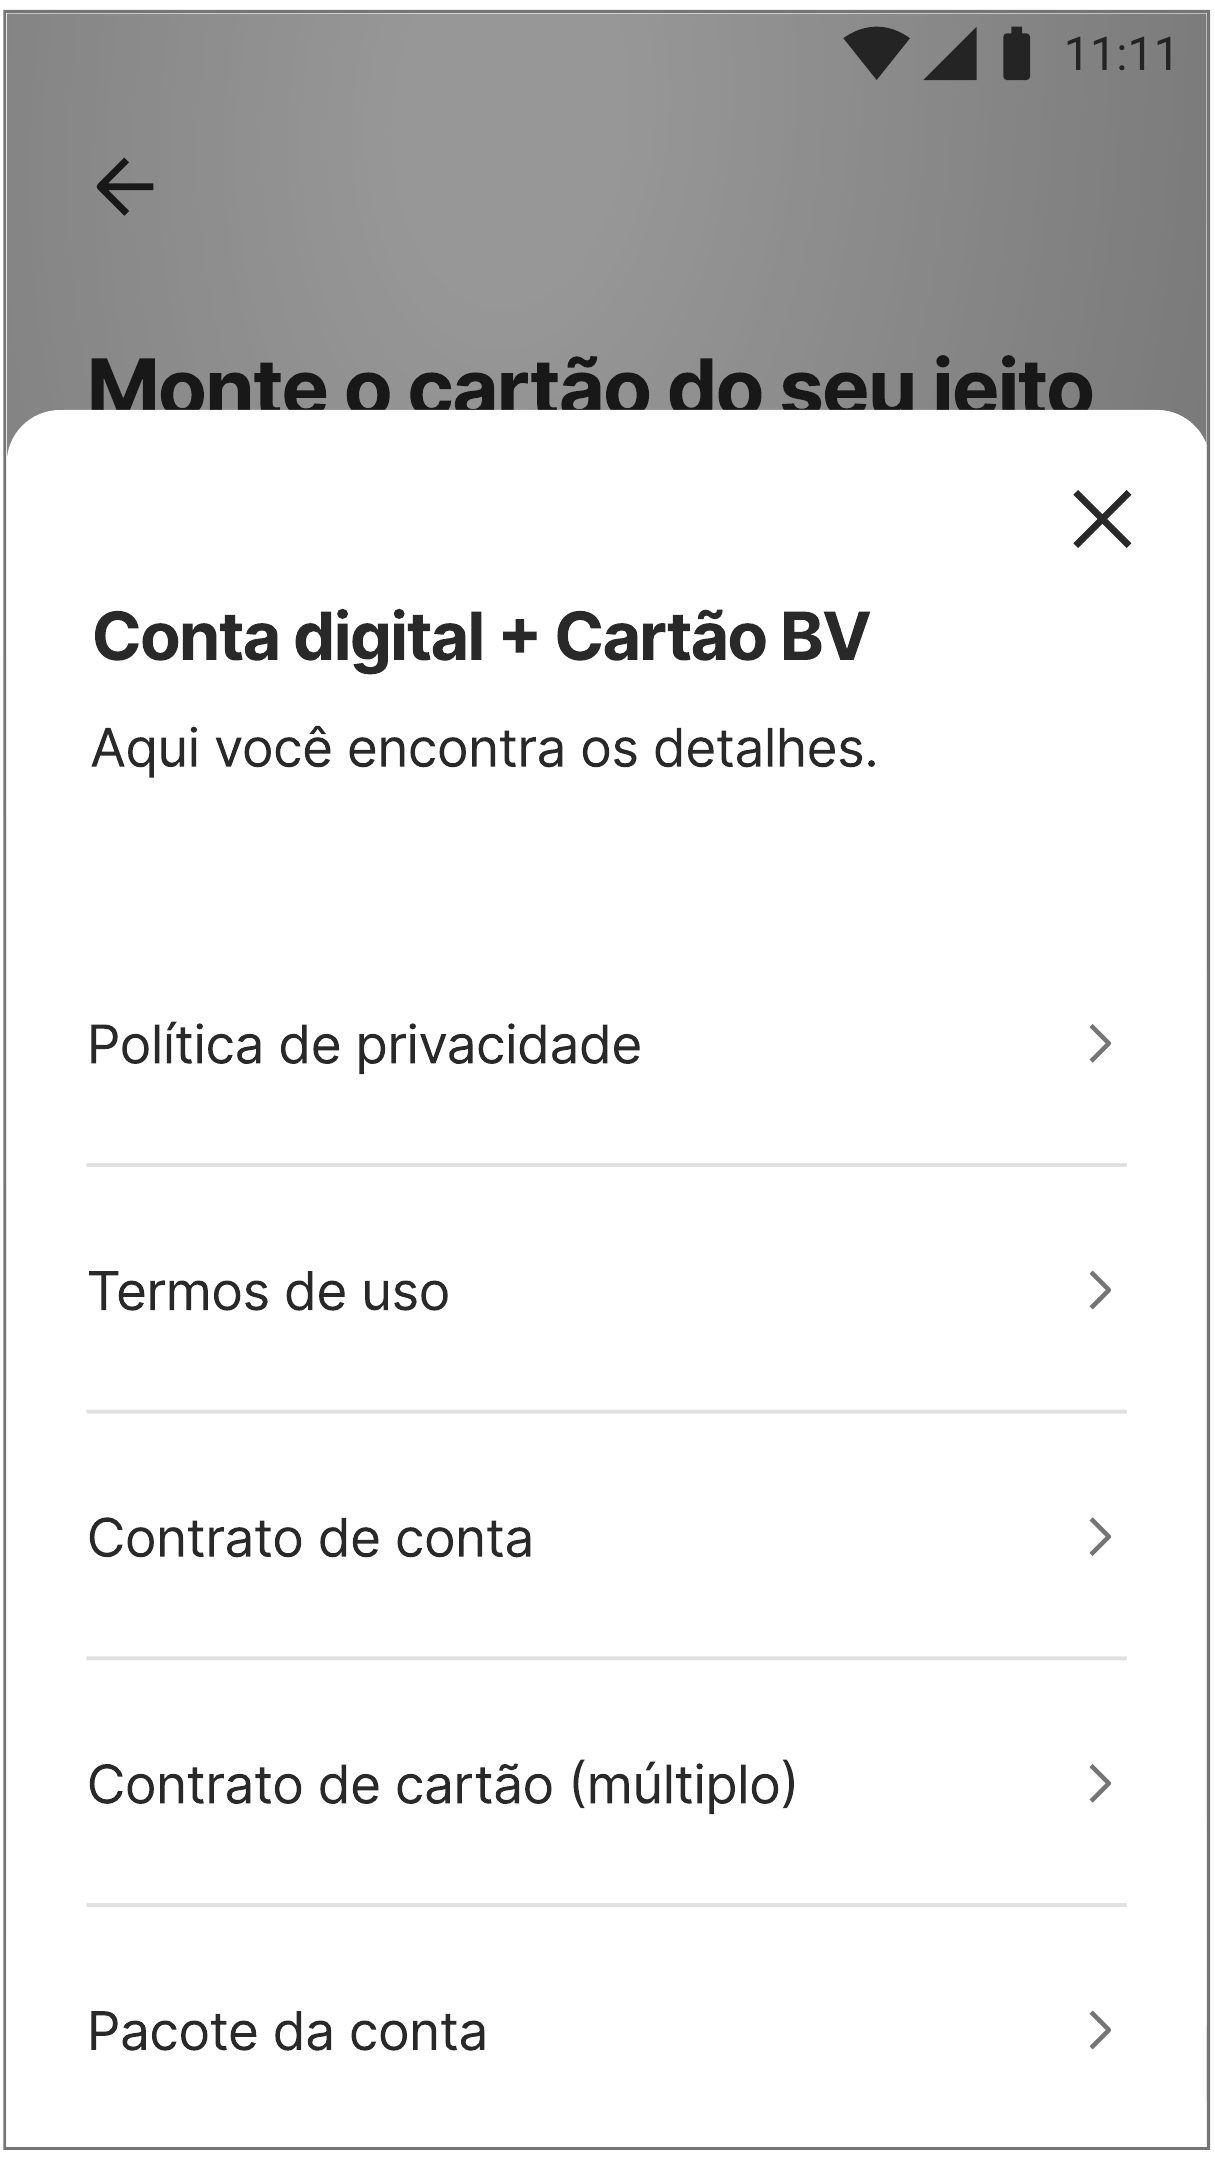
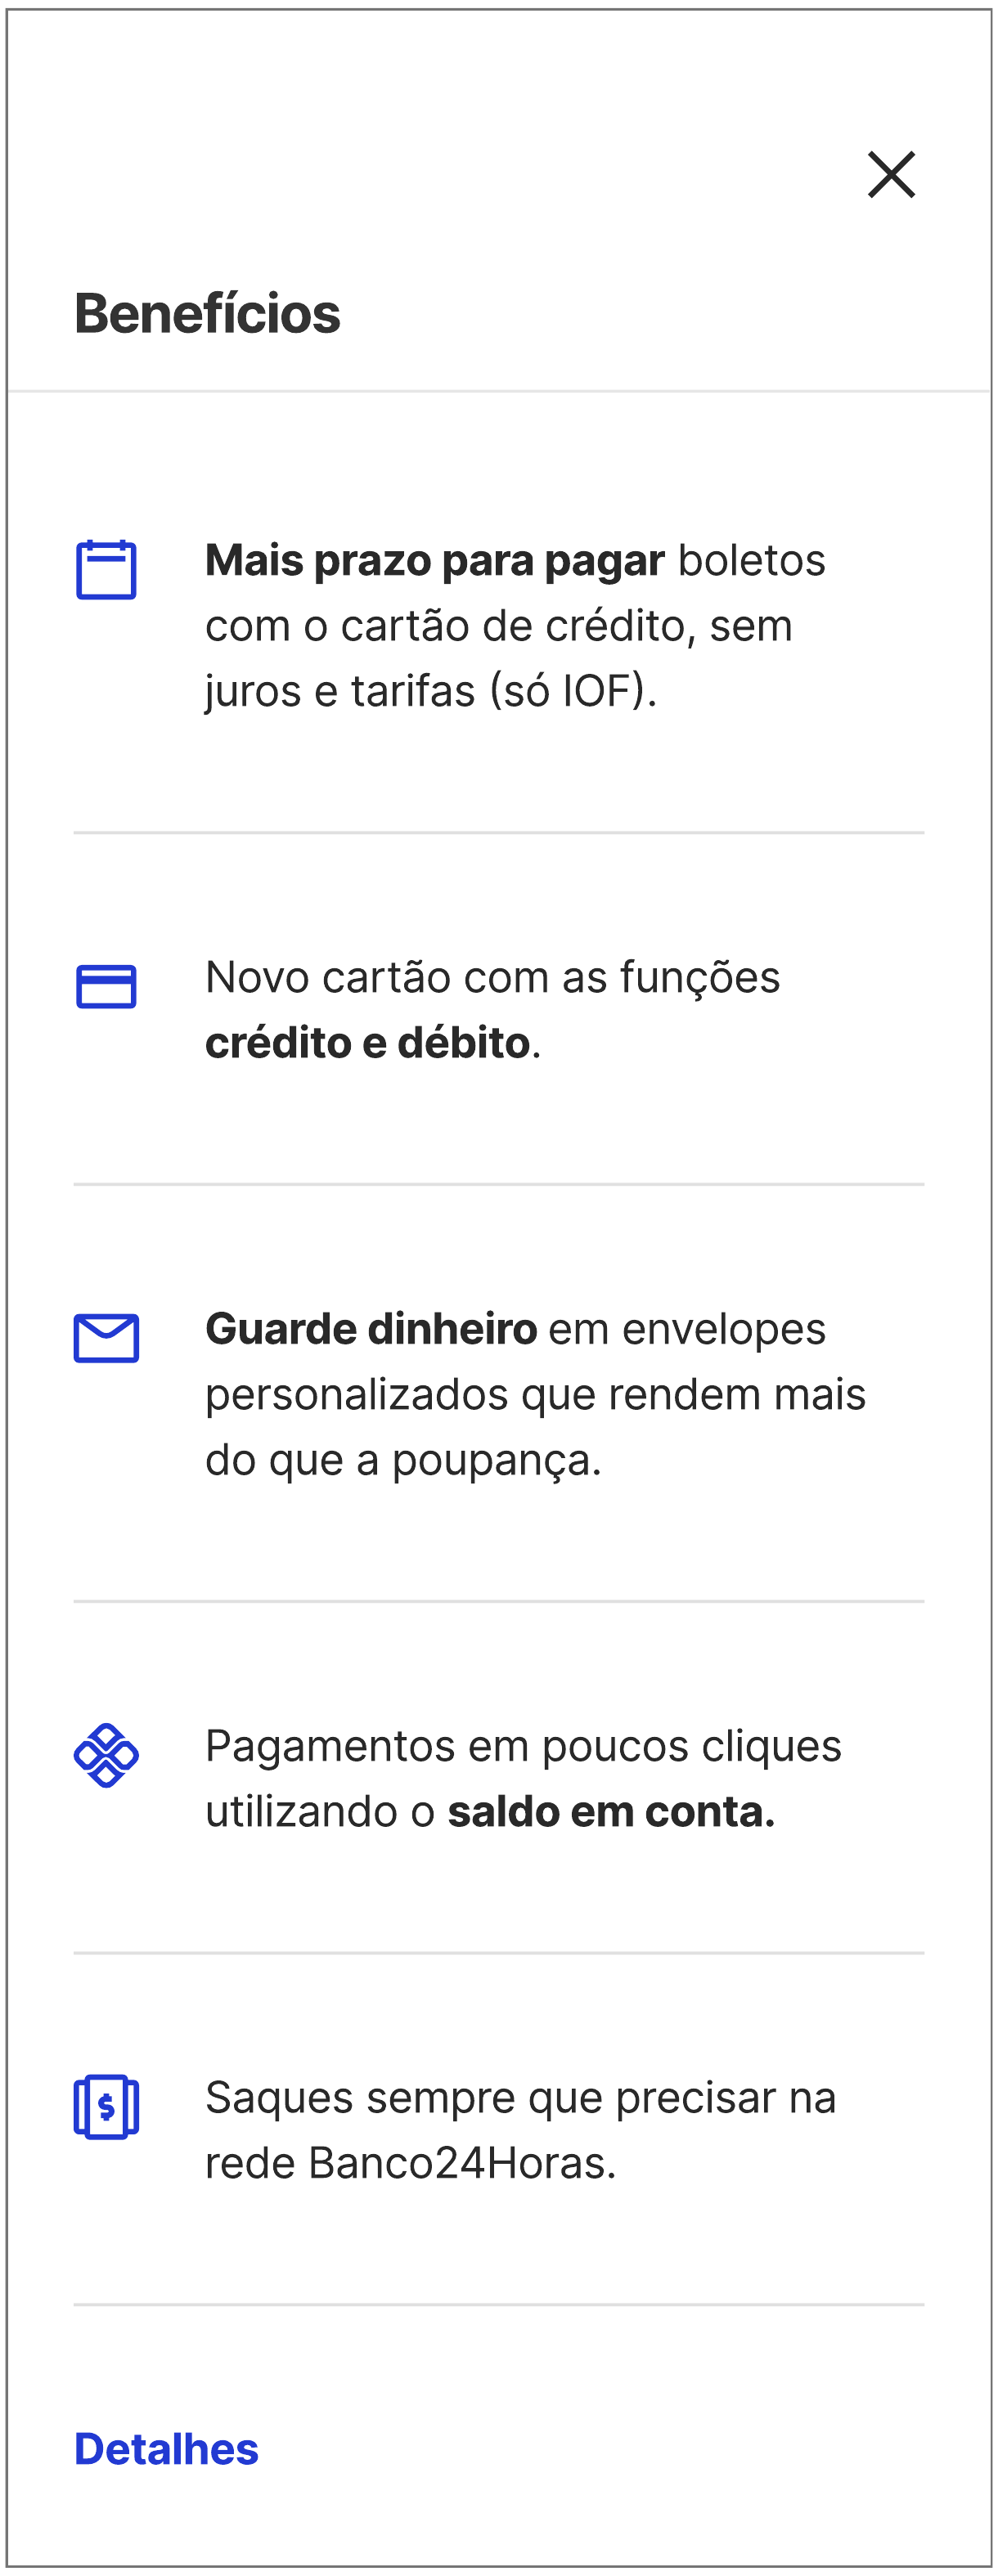
The experience continued into account and card setup. Clear terms and concrete benefits helped customers understand what they were accepting instead of experiencing the final step as a disconnected compliance interruption.
Next case
Itaú: Lending View ↘